“Be fearful when others are greedy and greedy only when others are fearful.” — Warren Buffett
The Greek physician Hippocrates is eternally associated with the directive that physicians must seek to heal or at least do no harm. In a very different context, as wealth managers, we strive to help clients achieve their long-term financial goals, the pursuit of which is facilitated by avoiding self-harm.
The temptation to deviate from asset allocation parameters by becoming overly defensive when stock values inevitably retrench, or to chase “winners” when narrow segments of the market surge, is powerful. Whether such responses are characterized as market timing, herd following, or excessive tactical trading, allowing prevailing sentiment and headlines to overly influence long-term, risk-based investment strategies can be destructive.
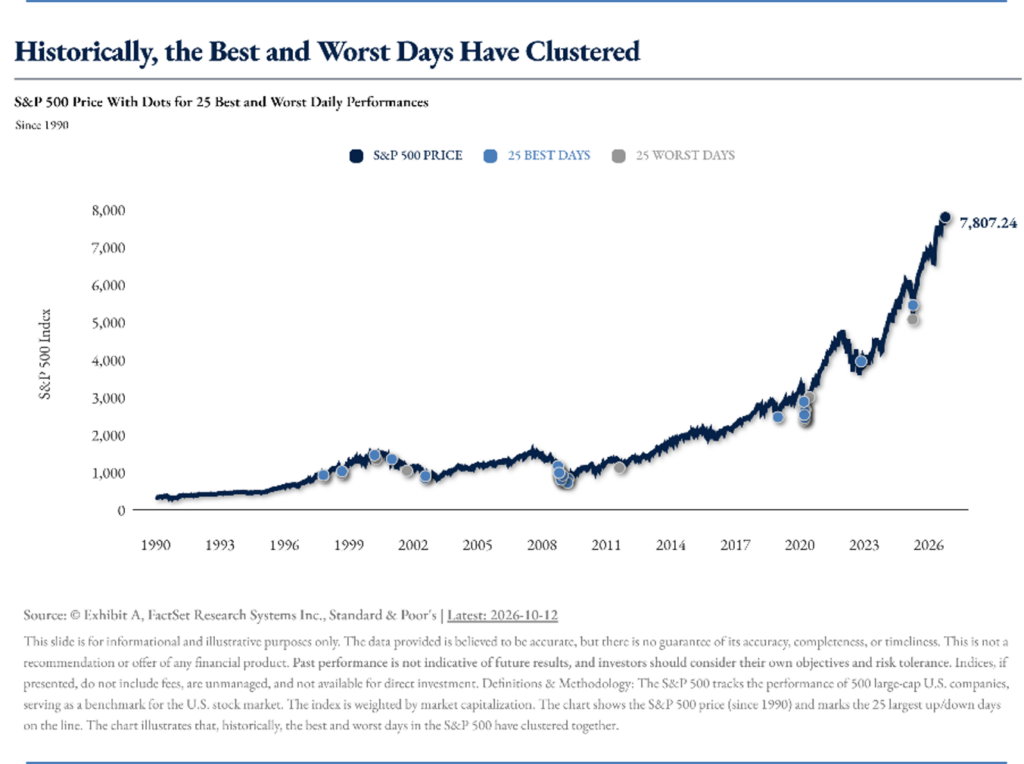
Calculating the costs of overly emotional decisions in either direction is very difficult given all the variables at work, although advisors often cite the impact of missing select highly positive days, many of which have historically occurred during bear markets. For example, missing the S&P 500’s 10 best days during 2006–2025 reduced annualized total returns by over 4%, compared with remaining invested throughout.
One may wonder how an investor could possibly miss just those “bounce back” days if perfect market timing is impossible. That’s a legitimate skepticism although it leads to a broader truth. As we often emphasize, volatility is a stock market feature, not a bug, and being in the market is far more beneficial than trying to time the market.
As the accompanying chart reveals, big up days tend to occur during the same time periods as sizeable declines. Reacting to short-term developments by panic selling, or “chasing the hot-dot,” can be counterproductive.
Tune Out the Noise
In statistical analysis, noise is defined as the random, unpredictable variability in data. While sudden market downturns may not be random in the sense that analysts usually attribute a specific cause, they are prone to unpredictability and rapid reversal.
Investors who impulsively react to volatility are effectively making two decisions every time they trade: when to sell and when to re-buy (or vice versa). The odds of consistently making those calls correctly are very low for professionals and personal investors alike, but the costs can be high.
Compounding: The 8th Wonder of the World
Albert Einstein has been credited with the making the statement referenced above, and math suggests he had a very good point. Consider a very simple example. If one starts with $100,000, invests for 20 years, and achieves an 8% annual return (compounded monthly), their balance will grow to $492,680. However, if market timing or other factors reduce returns to 6%, the investor’s balance after 20 years would be reduced to $331,020. This example illustrates how even modest differences in annual returns can compound over time, underscoring the value of maintaining a disciplined, long-term investment approach.
Overcoming Emotional Biases
Perhaps the greatest value of a trusted advisor lies in their ability to help investors pursue disciplined, sustainable investment strategies. At Appleton Wealth Management, we take pride in our investment research, security selection, and long-term risk-adjusted performance. However, we feel our greatest value lies in understanding individual needs. Through durable, risk-conscious asset allocation, we believe our clients are better able to make short-term volatility work for them rather than allowing it to harm long-term results.
Sometimes doing the simple things well matters more than trying to accomplish difficult tasks. Periodic portfolio rebalancing offers an example. Reallocating back to target asset allocation ranges may be unexciting, but it results in trimming more highly appreciated portfolio exposures and adding to underperforming ones. Doing so at the asset class level also enables security specific research within these broad exposures to add value.
Asset allocation is not static though. Circumstances change whether due to life stages, evolving income needs, inheritance, career developments, or other factors. Adjusting asset allocation may be warranted, although we feel it should be based on personal insight, not market sentiment.

This commentary reflects the opinions of Appleton Partners based on information that we believe to be reliable. It is intended for informational purposes only, and not to suggest any specific performance or results, nor should it be considered investment, financial, tax or other professional advice. It is not an offer or solicitation. Views regarding the economy, securities markets or other specialized areas, like all predictors of future events, cannot be guaranteed to be accurate and may result in economic loss to the investor. While the Adviser believes the outside data sources cited to be credible, it has not independently verified the correctness of any of their inputs or calculations and, therefore, does not warranty the accuracy of any third-party sources or information. Specific securities identified and described may or may not be held in portfolios managed by the Adviser and do not represent all of the securities purchased, sold, or recommended for advisory clients. The reader should not assume that investments in the securities identified and discussed are, were or will be profitable. Any securities identified were selected for illustrative purposes only, as a vehicle for demonstrating investment analysis and decision making. Investment process, strategies, philosophies, allocations, performance composition, target characteristics and other parameters are current as of the date indicated and are subject to change without prior notice. Registration with the SEC should not be construed as an endorsement or an indicator of investment skill, acumen, or experience. Investments in securities are not insured, protected or guaranteed and may result in loss of income and/or principal.