Insights & Observations
Economic, Public Policy, and Fed Developments
- September’s month-end spike in Treasury yields was certainly dramatic and is covered in length elsewhere in this update. The longer-term setup for the move deserves attention, however; much attention has been paid to the continued oil price pressures as the Iran war drags on with no obvious end. There has been recent progress here; the US Navy has been effective in the Strait of Hormuz and estimates suggest we’re likely getting 50% of prewar volume through Hormuz, and including pipeline alternatives overall is now up to around 80% of prewar norms. But the situation remains fragile.
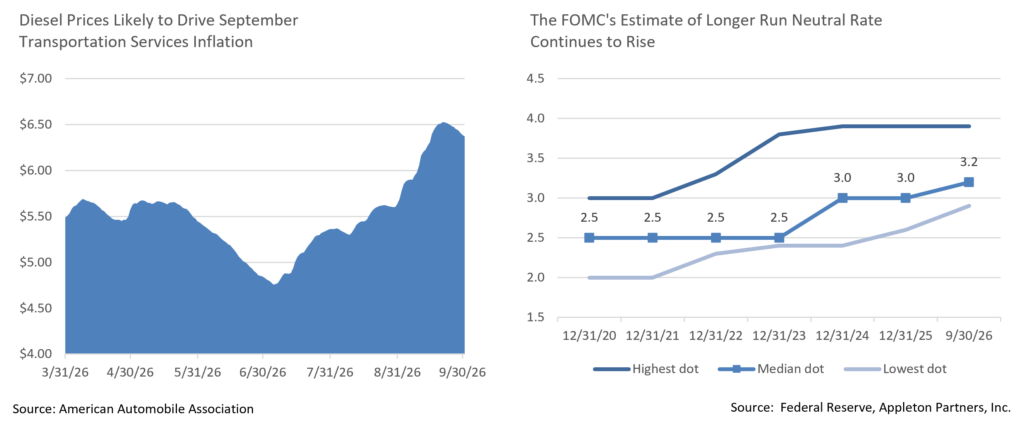
- Less attention has been paid to the long-term neutral rate, however, and we think this is another important factor. The FOMC’s assessment of what a “neutral” long term rate is for the US economy has quietly been shifting upwards for years. The current median dot, 3.2%, is higher than even the highest dot at year end 2020, and the lowest estimate today is still comfortably above the long-standing 2.5% in the post-Great Financial Crisis era. There are a number of possible reasons for this, though we would give strong consideration to national debt now exceeding 120% of GDP. But, in an environment where the neutral rate is approaching 4%, a historical norm of 100bps of curve steepness between the front of the curve and the 10yr does suggest long rates should be approaching 5%, as well. The market may not have been paying enough attention to this, and it appears to have now caught up.
- Thankfully, the economy elsewhere looks robust. Consumer spending remains extremely strong, with August retail sales well surpassing expectations at the headline, 1.2% vs 0.8%. Core measures were nearly triple, with ex Auto and Gas 1.2% vs 0.4% and “control group” 1.4% vs 0.5% control group. The Real Personal Spending report accompanying PCE was strong as well, a tenth over expectations at 0.6%. July’s weakness now increasingly looks like a blip. While there was some early evidence that high gas prices were dampening spending elsewhere, that increasingly looks to have faded.
- Inflation data showed nominal improvement last month, and in particular PCE fell from 3.3% to 3.0%. We’d suggest caution; the main driver here was a methodology changed that had been estimated to strip 0.2-3% off the headline. Cell services have been oddly hot for several months now and there’s growing price pressures in transportation services. This should only worsen next month, with AAA’s national average diesel price rising from $5.63 to a high of $6.51 over the month.
- After a shaky start in his first two meetings, Warsh did everything he needed to do in his press conference on the 16th. His continued refusal to provide not only forward guidance, but much of anything on Fed’s reaction function, remains a source of risk for longer rates and should increase the term premium, but he squarely put to rest any concerns he was trying to merely talk inflation down without doing anything. While he refused to answer a question on his estimate of the neutral rate directly, elsewhere he referred to the hike as removing “a dose of accommodation” and indicated he’d be “hard pressed to see conditions as restrictive,” strongly suggesting he thought we were below it and further hikes were likely. He also took an opportunity at his press conference to suggest his views were more hawkish than the averages expressed in the dot plot. Rates may have moved aggressively at the end of the month, but the week’s stability following the Fed meeting suggests this had little to do with Warsh.
Sources: U.S. Census Bureau, Federal Reserve, Bureau of Economic Analysis, American Automobile Association
From the Trading Desk
Municipal Markets
- September was a record setting month for municipals, albeit not in ways market participants were anticipating or hoping for. Underpinned by macro concerns about inflation, federal government fiscal concerns and the outlook for real rates, municipal rates sold off violently to cap a month that recorded the worst monthly performance for the asset class since 2008 as measured by the Bloomberg IG Tax-Exempt Index.
- On the back of a significant US Treasury selloff, municipal activity was amplified by substantial tax-loss harvesting activity in the secondary market that led to disproportionate down moves and substantial underperformance relative to Treasuries. Municipal yields rose by anywhere from 53bps to 102bps in a descending fashion, with the front end underperforming all other parts of the curve and setting up comparisons with other notable market-resetting events like the COVID shut-down and “Liberation Day.”
- The municipal curve bear-flattened dramatically in September as front-end yields skyrocketed to twice the move seen by the long end of the curve. The 2-10s slope flattened by 28bps, with the 2-5 segment accounting for 11bps of that move. The 2-30s slope flattened by 48bps to close the month at 159bps, fully offsetting the steepening we had seen prior to September.
- Ratios cheapened across the board but inside of 5-years on the curve saw double digit repricing, with the 2-year getting cheaper by 14.5%, the 3-year by 12.75% and the 5-yr by over 10%. Parts of the curve starting in 7-yrs saw relative cheapness of 3.4-8% in a descending fashion and September closed the month with all maturities out to and including the 10-yr seeing ratios > 70% to USTs. The long bond ratio closed the month at over 91% of its taxable counterpart.
- Despite the volatility that dominated the market and some issuers consequently choosing to postpone their deals, supply of long-term tax-exempt debt totaled $52B, setting a record for September issuance according to JP Morgan.
- While preliminary, September shows as a positive inflow month of approximately $5.2B coming into the asset class as noted by JPM, totals are subject to change and may even drive the totals into negative territory as funds that report less frequently are set to publish their numbers.
Corporate Markets
- September turned out to be an extremely volatile month for Treasury yields. After ending august at 4.75%, yields rose slowly in the lead up to the September FOMC meeting, testing resistance at 5%. This level held after a well-received Fed Funds rate hike but broke abruptly one week later. The impetus may have been hotter than expected S&P PMI reports, but these were only modestly stronger than expected and this is not normally a market-moving release; simple fatigue and capitulation after a month of rising oil prices and concern about the long-end was more likely the primary reason. The 10yr ultimately set an intra-day high of 5.30% before closing the month at 5.28%. This represents the highest yield offered by the 10yr Treasury since 2007, before the Great Financial Crisis, nearly twenty years ago.
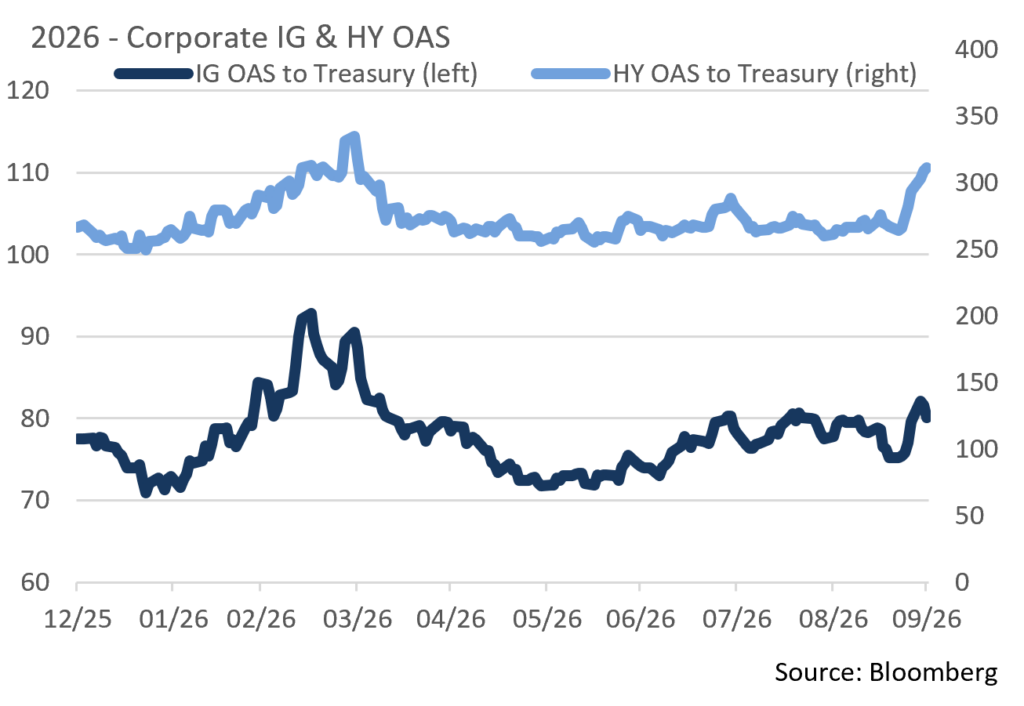
- US Investment Grade credit spreads remained range-bound and proved to be resilient given the volatility in US Treasury rates over the month. The Bloomberg US IG Corporate OAS moved just 3bps higher, reaching 80bps, with the high on the month of 82 bps, 7bps off the monthly low of 75bps. September month-end spread levels sit right on the YTD averages with the highs hitting back in March, still well below the 5yr average of 112bps. We do seem to be close to an inflection point. Pressure from US Treasury rates, further economic uncertainty, and another Fed Funds rate being priced in before month end could create a pause in demand for Investment grade bonds, allowing spreads to move slightly higher. While we remain cautious, we continue to manage keeping with our quality and duration bias.
- The rapid pace of issuance so far in 2026 began to slow as the month progressed. The $195B in issuance fell short of the $215B the market expected. A lower quality jumbo M&A deal brought by Paramount did garner lots of attention on the last day of the month. The $30B deal was the 6th largest on record and the largest since Amazon’s $37B deal back in March (4th largest on record). Demand reached 3.6x the amount of bonds available. Investors gravitated to the shorter/intermediate tranches driving some long end attrition which reshaped the deal overall. The technical backdrop of the investment grade primary market continues to be stable, but issuers are moving with caution given absolute yield levels, as well as the overarching theme of rate volatility. Expectations are for a slowdown in issuance in October and possibly the balance of the year.
Sources: Bloomberg, Bond Buyer, Barclays, JP Morgan, and Lipper Inc.
Public Sector Watch
Muni Credit Conditions & Higher Rate Environment
As investors and investment managers digest the march upwards in fixed income rates, we at Appleton believe it is important to highlight that:
- as investors evaluate the current yield opportunities, municipal credit fundamentals are strong and,
- well-managed municipal issuers can handle the higher rate environment.
Muni Credit fundamentals remain healthy despite emerging budget pressures
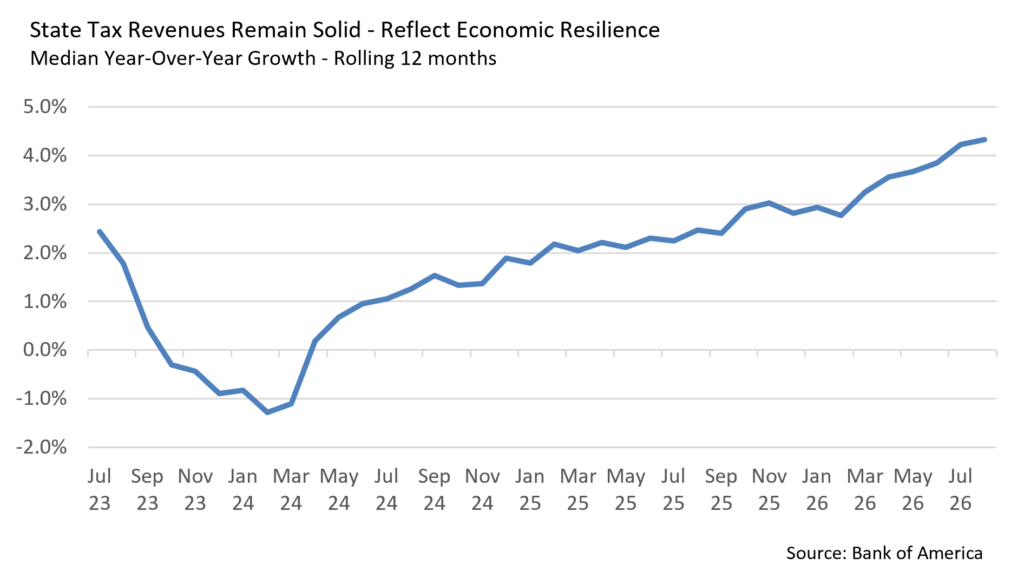
Credit fundamentals heading into year-end 2026 remain strong, with positive revenue performance, conservative budgeting, better-funded long-term liabilities, and healthy balance sheet reserves all sustaining municipal credit quality. We are seeing some challenges emerge, such as narrowing margins, out-year deficit projections and rising costs for labor, healthcare and utilities. Despite these developing pressures, most investment grade municipal issuers are well-suited to manage the current elevated rate environment.
Impact of Higher Rates
The simple equation is that higher rates result in increased borrowing costs for municipal issuers. However, the actual impact is more nuanced.
We expect those issuers with flexibility to delay, reduce or restructure borrowing plans in the face of higher borrowing costs. Separately, current rate levels of 4-5% are not unprecedented. Municipal issuers have borrowed at rates similar to today’s and have done so without hurting their credit profile or finding their way into distress. Another aspect to consider is that most municipal issuers sell bonds at fixed rates and an elevated rate environment does not reset the costs for the entire debt stack. Issuers that are borrowing at 5% today, for example, also have debt outstanding that was issued at much lower rates over the previous 5-10 years. For most large municipal issuers, higher rates work themselves into overall debt costs over a multi-year period.
Issuers & Sectors Most At-Risk to Higher Rates
The issuers most at-risk are the weakest credits, particularly those with an immediate need to access the capital markets, are reliant on one speculative or single-site construction project, and those that are highly leveraged compared to revenues. High-quality municipal issuers are not immune to higher rates but certainly have balance sheet flexibility to either wait it out, cash-fund capital expenditures, or use shorter structure debt that can possibly be refinanced at lower rates in the future. Examples of sectors that are most sensitive to higher rates are those that have some reliance on real estate markets. These include housing agencies, land secured (also known as “dirt deals”), and senior living where a resident may need to sell their home to afford the entrance fee. Notably, Appleton’s exposure to housing is minimal and we have not actively participated in the land secure and senior living sectors.
Sources: Bloomberg
This commentary reflects the opinions of Appleton Partners based on information that we believe to be reliable. It is intended for informational purposes only, and not to suggest any specific performance or results, nor should it be considered investment, financial, tax or other professional advice. It is not an offer or solicitation. Views regarding the economy, securities markets or other specialized areas, like all predictors of future events, cannot be guaranteed to be accurate and may result in economic loss to the investor. While the Adviser believes the outside data sources cited to be credible, it has not independently verified the correctness of any of their inputs or calculations and, therefore, does not warranty the accuracy of any third-party sources or information. Any securities identified were selected for illustrative purposes only, as a vehicle for demonstrating investment analysis and decision making. Investment process, strategies, philosophies, allocations, performance composition, target characteristics and other parameters are current as of the date indicated and are subject to change without prior notice. Not all products listed are available on every platform and certain strategies may not be available to all investors. Financial professionals should contact their home offices. Registration with the SEC should not be construed as an endorsement or an indicator of investment skill, acumen, or experience. Investments and insurance products are not FDIC or any other government agency insured, are not bank guaranteed, and may lose value.